Showing posts with label CI Holdings. Show all posts

Wednesday, March 28, 2012

CIHolding

Disposed CIH at RM1.25. Its better for me to avoid uncertainty of their future business.

Tuesday, August 9, 2011

Raise some cash..

Took some profit from my CI Holding for 31% gain, just to raise my cash level ~<40% - -. Balance plan to keep due to good deal with Asahi. Hope i could collect again...cheaper.
Now, i can sleep well, if market going north, at least profit already in my hand. :)

Sunday, August 7, 2011

C.I. Hldgs searches for new core business

Interesting article. Im also excited for CIH new venture. Well, some analyst speculates that they might venture into snack/biscuit manufacturer, property and automotive distributor company, well out of all option, i strongly support if they want to venture into snack/biscuit manufacturers.

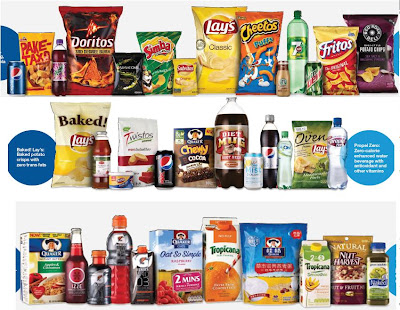
Since the MD has vast experience in F&B industry, it would be definitely be an advantage to the group, rather than venturing into uncharted territory for the group like automotive company. The margin is good plus since they have good and established relationship with Pepsi Co through Permanis, im sure it wont be an issue for them to bring in other Pepsi Co products like Frito Lays' etc.

================================================================================

###############################################################################

C.I. Holdings Bhd is exploring investment opportunities across various sectors, including potential investments in fast moving consumer goods (FMCG), its area of expertise.

Managing Director Datuk Johari Abdul Ghani told Bernama today that the company is focused on acquiring a controlling stake for a new core business for C.I.

C.I. has been in search of investment opportunities since it inked a proposed deal to sell off its wholly-owned subsidiary, Permanis Sdn Bhd, which provided a strong core business since the company was established.

Permanis contributed over 90 per cent to C.I.’s profit and revenue. On July 21, C.I. signed an agreement with Japan's Asahi Group Holdings Ltd, to sell Permanis for RM820 million cash.


"Since our announcement, we have received many proposals and continue evaluating them. The proposals received so far have spanned a broad range of industries including FMCG.

"At this point of time, we are not ruling out anything and will consider any new proposal received.

"However, we are focused on proposals where we can take a controlling interest. Hence, we also feel that it is important to take our time and consider each proposal carefully," Johari said.

He said C.I. is still deliberating and has yet to determine the utilisation of proceeds from the disposal of Permanis.

"We are mindful that the allocation of the proceeds must take into consideration the interest of the company and its shareholders," he added.

He is the single largest shareholder of CI with a 30 per cent stake.

Syed Khalil Syed Ibrahim and his mother, Datin Mariam Prudence Yusuf, collectively hold a 20 per cent equity interest in the company.

Johari said the company is in the midst of preparing a circular to obtain approval from shareholders for the disposal of Permanis.

"We expect to be in a position to issue the circular to shareholders in October and the extraordinary general meeting will take place 21 days thereafter," he added.

He said the company will release the results of its financial performance for the fourth quarter and full year on Aug 25.

For the financial year ended June 30, 2010, the company turned in a net profit of RM38.17 million on revenue of RM516.4 million.

C.I.posted a net profit of RM11.37 million on revenue of RM140.42 million for the fourth quarter of its financial year 2010. -– Bernama


Tuesday, July 19, 2011

C.I. Holdings - I love it


CIH Holdings is the owner of Permanis since 2004 and has restructured the company from a lousy to a growth company, and now contributes almost 90% to group earning.

Brand Under Permanis = PEPSI, DIET PEPSI, TROPICANA TWISTER, LIPTON TEA, 7UP, BLUE MINERAL WATER, MOUNTAIN DEW, REVIVE ISOTONIC, BOSS COFFEE, MIRINDA, FROST & CHILLS.

Since the management already mentioned that they would like to expand further into full fledged F&B business, im expecting that they would like to introduce Frito Lays and Quaker Oat products more aggressively into Malaysian market. PepsiCo is widely know as the largest snack company through Frito Lays company. Thus, by having snack/food manufacturer company under CIH, would definitely complement their current business and create a better value to shareholders.

However, my only concern is acquisation of Permanis by Asahi, hopefully the management will put stop of this.

p/s = Tropicana Twister - Lychee, dont really like it, Fruit Tree Lychee much better. :p


Saturday, June 11, 2011

Portfolio Update June 2011


My portfolio still unchanged consist of Mahsing, SOP, CI Holdings and YTL Power-WB. Portfolio 1 is badly hurt due to poor performance of C.I. Holdings, mostly due to impact higher cost impact from removal of sugar subsidy and YTL Power-WB on cautious over their YES business, however portfolio 2 is performing well, thanks to Mamee's SCR and SOP. :)

Portfolio 1 - YTD gain is drop from 17% gain in february to ~4%
Portfolio 2 - YTD gain is 16.5%.

Both still outperforming KLCI gain this year.


Wednesday, May 11, 2011

New Job, New Apt...

Fuh, new job, new apt, no internet, its been tough for me for last few weeks. Anyway, i have disposed Padini and swap to CIH @ 2.48.

Thursday, April 21, 2011

Squeezed CIH ..again


Collected another C.I. Holding at RM2.93 and Padini @ RM1.04. Disposed Mamee @ 4.22. Privatisation going to take another 6 months..>18% is quite ok already for me.

Sunday, March 20, 2011

Malaysia's Nonalcoholic Beverage Market

Source: CIMB Research

It is exciting to know that Coca Cola company want to invest and expand their production in Malaysia. Well, it is a good sign that the local F&B industry has a bright future due to growing population, rising middle class income, a lot of untapped 'territory' looking at low beverage consumption per capita in comparison with regional market. So, theres a tremendous growth opportunity for local F&B players.

KO think that ..

"
Growth in Malaysia's nonalcoholic beverage market has been relatively slow at between 4 and 6 percent over the last five years, compared to double-digit growth in some other regional markets. He attributed this to a lack of aggressive competition and insufficient diversity in the product range."

I couldn't agree more. I'm not sure regional market but in Japan, there are a lot of product variates in the market. The leader of course KO, Suntory, Kirin and Sapporo..just to name a few.

I do hope Permanis will launch more new products in the market. Since they have good relationship with PepsiCo and Suntory, i think there a lot of new brand product opportunities that could be explore for Malaysian taste.
I really like the new Permanis management compare to many years ago as now they have more clearer guideline in which market they want to be in. The management already mentioned that CIH want to see contribution from non-soda market, like juices and healthy drink by more than 50%.

Looking at PepsiCo and Suntory product lines, i think it is possible to achieve that vision in next few years. Since production line and warehouse is expanding, i hope they will introduce more products from suntory like DAKARA (protien water, vitamin water etc) and C.C. Lemon. Being a health conscious, I really enjoys Dakara..and Boss of course when i was in Japan....Oh, and starbuck too. :p


===========================================================
Coca-Cola Investing $302M In Malaysia
By Eileen Ng, Associated Press Writer
Manufacturing.Net - March 16, 2010

Printer Friendly E-mail to a Colleague

NILAI, Malaysia (AP) -- Coca-Cola said Tuesday it will build a new bottling plant in Malaysia and invest 1 billion ringgit ($302 million) over the next five years to boost growth in the Southeast Asian market.

The investment comes as the world's largest soft drink maker gets ready to end its franchise with a local bottler after sales remained stagnant over the years.

Coca-Cola Co. is expected to let its decades-long contract with a unit of Singapore's Fraser and Neave expire in September 2011. The contract, which covers mainly the bottling and distribution of Coca-Cola and Sprite brands, was worth 421 million ringgit ($127 million) a year.

Glenn Jordan, president of the company's Pacific Group, said in an interview with The Associated Press that a third of the 1 billion ringgit will be invested in an eco-friendly plant on a 30 acre (12 hectare) site in the southern state of Negeri Sembilan.

The rest will be plowed into sales and merchandising assets, product innovation and marketing to beef up the company's presence in Malaysia, where the annual per capita consumption of Coca-Cola is well below that of many countries in the region, he said.

The plant is expected to be operational by mid-2011, he said.

"This investment will enable us to support our core brands, Coca-Cola and Sprite, enhance our competitive edge and increase our geographic coverage," he said.

Jordan said Malaysian investors have 15 percent stake in the new bottling facility, with the Armed Forces Fund Board holding a 10 percent stake and private firm AAD Equity, led by former finance minister Daim Zainuddin, 5 percent.

The investment will directly create 600 to 800 new jobs at the bottling plant, and is expected to create between 6,000 and 8,000 jobs with local suppliers, he said.

Jordan said Coca-Cola's move to end its franchise with Fraser and Neave was an "amicable separation" as both companies have different growth strategies.

He said growth in Malaysia's nonalcoholic beverage market has been relatively slow at between 4 and 6 percent over the last five years, compared to double-digit growth in some other regional markets. He attributed this to a lack of aggressive competition and insufficient diversity in the product range.

"We are here to revolutionize the way we sell our products. We see a lot of opportunities here," Jordan said. He declined to give growth targets but said the company aims to achieve "healthy growth" and be more competitive in Malaysia.

At the groundbreaking ceremony of the plant earlier, Prime Minister Najib Razak welcomed Coca-Cola's long-term commitment to Malaysia.

"I take it as a strong signal that the world's most recognized brand is expanding in this important market and enhancing its contribution to the Malaysian market," he said.

Friday, March 4, 2011

CI Holdings & Leader


Disposed my last Leader today at average ~0.84 for a peanut profit. Very disappointed with Q4 result, & Squeezed C.I. Holdings into my portfolio at RM3.02...finally. I think this level is pretty safe.


Tuesday, February 1, 2011

Commodity

Mamee Cost Breakdown

If we compare cost breakdown between Mamee and CI Holdings, i think CI Holdings will be more effected by rising commodity as sugar does not really a significant cost factor to Mamee. Cooking oil also at manageable level but flour price is quite a concern to me as flour contribute 11% in their cost breakdown. However, wheat price is still lower than 2008 price while sugar is trading at 10 years high. As Mamee does not use subsidised flour, i think they are more well prepared in cost controlling. Will avoid CI Holdings for time being as i want to wait for next quarter. The cost impact of sugar should be reflected in 2 quarter result, will see whether they are as good as F&N at cost management. Maybe i should start accumulate mamee first?

Mamee cost breakdown


Wednesday, January 5, 2011

CI Holding (2828)

C.I. Holding operates in three segments: Beverage, Building and construction related products and Investment holdings.Who doesn't know Pepsi, Mountain Dew, 7Up Revive and Blue (mineral water). Their management has done a great transformation from quarry, building material and loss making to a solid beverage and construction produc company ans still growing at healthy rate. 5 Years CAGR ~14% (revenue)

We can see the growth trend from the chart. Btw, sudden increase in revenue FY04 vs FY05 mainly to sales of the their newly acquired beverages division, while the higher loss in Q4 FY04 was mainly due to the recognition of loss on disposal of C.I. Enterprise Sdn Bhd a wholly-owned subsidiary of RM35.509 million and impairment loss of goodwill of the quarry division of RM20.464 million.

...will write later..too lazy to write.. :P