Showing posts with label portfolio. Show all posts
Showing posts with label portfolio. Show all posts
Wednesday, March 28, 2012


Monday, March 19, 2012
Wednesday, February 22, 2012
Tuesday, February 7, 2012


Tuesday, January 31, 2012
Monday, January 2, 2012
2011 review and Happy New Year 2012
Nothing much to write, just review of 2011 return. Well, my YTD performance following Japanese calender year (Apr-Mar), but just to keep a record my past year performance.


Well, portfolio 1 (Heavyweight - Mahsing) posted negative -4% return. Strong performance of Mahsing last year, end 2010/early 2011 but lower return in end of 2011 despite the company able to post uninterrupt earning growth. Negative performance mostly due to softening property market.
However, portfolio 2 (defensive play - heavyweight, CI Holding) managed to outperform KLCI by more than 95%, thanks to M&A exercise this year.
Overall, managed to outperform the market, thanks to privatisation of Mamee, Permanis, SP Setia and KFC Holdings. 2011 turned out to be my lucky year but 2012.....i think going to be very challenging...but looking forward for it.
Wednesday, December 14, 2011
QSR, KFC get takeover offers
CVC Capital Partners Ltd teamed up with Johor Corp to make buyout offers today for KFC Holdings (Malaysia) Bhd and parent QSR Brands Bhd, which operate more than 900 fast-food outlets in Southeast Asia and India for brands including KFC and Pizza Hut. London-based buyout specialist CVC and Johor Corp, an investment arm of Malaysia’s Johor state government, offered RM4 per share for KFC Malaysia and RM6.80 per share for QSR, according to separate filings to the Kuala Lumpur stock exchange today. -- Bloomberg
============
Thanks to god, this is my forth luck this year, first mamee, then Permanis, then SP Setia-WB and now KFC.
Monday, December 12, 2011


Thursday, December 1, 2011

Tuesday, November 1, 2011
The Edge Billion Ringgit Club - Mah Sing Group Bhd
| Written by Financial Daily |
| Tuesday, 01 November 2011 11:37 |
Incorporated in 1991, Mah Sing Group Bhd is one of Malaysia’s leading developers. With numerous international and domestic awards, the group has established a strong brand in medium to high-end landed residential properties, commercial projects including office buildings, shops, retail and SoHo as well as industrial projects. It also has a profitable plastic business, which was the original core business of the group before it diversified into property development. The group has about 34 projects across Malaysia.
Group managing director and CEO Tan Sri Leong Hoy Kum shares with The Edge Financial Daily his strategies and dreams for the company.
TEFD: What are the group’s competitive strengths and advantages?
Leong: Our competitive strengths include being versatile, having a strong brand, being innovative and being able to cater for various market segments.
• Versatility. Mah Sing is one of the few developers in Malaysia to offer a wide range of products comprising residential (catering for a wide range of customers, from medium to high-end developments, both landed and high-rise with built-up areas from 500 square feet), commercial (office, retail and shops) and industrial properties. Our wide ranging product offerings help the group identify and roll out different products in different phases of the economic cycle (see table).
• Quick turnaround strategy. The group ensures a short period between land purchases and launches for fast cash flow generation to maximise shareholders’ return.
• Strong research and development team. We conduct in-depth study of market needs. The team is able to identify new trends that appeal to the market. For instance, in the residential segment, we identified the trend and appeal of superlink, semi-detached and bungalow developments in a gated-and-guarded environment with facilities. In the commercial space, we popularise en bloc sales in the primary market (The Icon Jalan Tun Razak — West Wing and East Wing, and Apex Tower, Southgate). For the industrial segment, the group identified the opportunity for niche semi-detached industrial properties in the Klang Valley which resulted in the brisk sales for our iParc 1, 2 and 3
• Strong branding. The group has built a strong brand name over the years, delivering quality products on a timely basis that meet the needs of end buyers.
 |
| Leong is inpired by Li Ka Shing and aims to make Mah Sing the Cheung Kong of Malaysia one day. |
 |
• Innovative and fresh concepts, adaptable to changing market demands. Our product development team continuously work on innovative products based on market feedback obtained by our research and development team. While presenting fresh concepts, we ensure that practicality is given paramount importance.
• Quality and services. Mah Sing has a strong quality control and quality assurance team that ensures all our projects meet and exceed stringent quality standards. We are also adopting international best practices in ensuring quality and have sought CONQUAS (Construction Quality Assessment System) certification by BCA Singapore (Building and Construction Authority) for all new residential projects. We also have the distinction of being the first and only developer accorded the CONQUAS award for an office building in Malaysia, namely The Icon Tun Razak which was completed in 2009.
• Strong balance sheet and earnings sustainability. We had low net gearing of 0.32 times as at March 31, 2011. This provides us with the capacity to gear up for landbanking. Our present combined remaining gross development value and unbilled sales are about RM14 billion which should provide earnings sustainability for another five to seven years.
• Geographical diversification. Domestically, Mah Sing has developments in the three main growth corridors of the Klang Valley, Johor and Penang. It is also looking at opportunities abroad in China, Vietnam, Singapore and Australia.
What are the group’s achievements in the past four years?
Our revenue doubled from RM573 million in 2007 to RM1.11 billion in 2010, while net profit increased nearly 50% from RM81 million in 2007 to RM118 million in 2010. Our number of projects nearly tripled, from 13 projects in 2007 to 34 in 2011. We have maintained a consistent dividend payout of a minimum of 40% of net profit since 2006. Mah Sing has garnered both local and international awards and accolades for its projects as well as recognition for its performance as a leading property developer.
How is the group positioning itself within your industry? What are your strategies to grow or gain market share?
Mah Sing is a premier lifestyle developer and our expertise is in innovative product development, high quality finishing and timely delivery of products that surpass our buyers’ expectations. We are also one of the very few developers in the country to offer a full and complete range of properties, namely residential, commercial and industrial products. Hence, we are positioning ourselves as a one-stop centre where properties are concerned.
We will continue to offer properties in good locations, with concepts and designs that meet buyers’ needs. In 2007, we achieved sales of RM727 million and doubled that to RM1.5 billion in 2010. Moving forward, we aim to gain more market share, starting with a RM2 billion sales target for 2011.
We are committed to raising the bar to continuously improve our concepts, designs and also strive to create iconic buildings and developments. We will also continue to run our business well, grow our revenues, profits and returns to shareholders, as well as adopt good corporate governance.
What are the group’s plans for the future?
In the coming years, the group will proceed with its three-pronged strategy. We will continue with our niche, quick turnaround development model for our residential, commercial and industrial series as it is profitable and cash-generative. With our low net gearing, we target to acquire a large tract of strategic land bank over the next two years. In the future, we shall explore overseas expansion to drive future earnings growth.
What is your dream for your company? How would you like to see it in 10 years?
My vision is to be a regional developer. We would like to continue with our branding locally and hopefully someday, our brand will penetrate other parts of the world. This is what we wish for as we are looking at bringing value to the house buyers, improving the quality of life and enhancing their lifestyles. We are a dynamic company and seek continuous improvement. Ultimately, we want to leave a legacy of excellence.
I am inspired by business luminaries like Li Ka Shing and aim to make Mah Sing the Cheung Kong of Malaysia one day.
Monday, October 24, 2011

Monday, October 10, 2011
Raising some cash

Took some (30%) profit on my Mahsing @ RM1.80. Holding too much property stock make me nervous looking at current uncertainty. Well, there's nothing new and exciting news from europe, thus, its better for me stay in sideline.
Friday, September 30, 2011
Sold SP Setia-WB

Wednesday, September 28, 2011
My third Luck.... now SP Setia
I'm a bit excited when i notice the share of SP Setia being suspended this morning, as i had similar experience/situation with Mamee early this year and C.I. Holding, mid of this year. So, first Mamee, then Permanis, now SP Setia.
Consider myself very lucky with latest PNB move to acquire SP Setia at RM3.90 and RM0.91 for its warrant. Honestly, i think the offer is undervalue for a good and a darling for local and international funds. Hope they will revised the offer at much higher side, at least RM4.00/share.
Nonetheless, im still happy as @RM0.91, im making ~139% gain in short time.(if share were traded near the offer) :p
Monday, September 26, 2011
S P Setia posts strong numbers yet again


Will collect more if its down again. I think SP Setia is the only giant property developer currently sitting on net cash, good landbank (local and o/sea) and mix combination of mid and high end residential and commercial development.
Maintain buy at RM3.19 with fair value of RM5.41: We reaffirm our “buy” rating on S P Setia with our fair value unchanged at RM5.41, at par to its fully-diluted NAV estimate.
===============================================================
S P Setia Bhd
(Sept 23, RM3.08)
Maintain buy at RM3.19 with fair value of RM5.41: We reaffirm our “buy” rating on S P Setia with our fair value unchanged at RM5.41, at par to its fully-diluted NAV estimate.
S P Setia reported 3QFY11 earnings of RM91 million, taking its 9MFY11 net profit to RM246 million, or a robust growth of 39% year-on-year. This is well within our estimate, covering 78% of our full-year earnings projection of RM311 million although it came way above consensus estimates by 12%.
At a glance, earnings were flat quarter-on-quarter. However, stripping off the RM32 million gain from the sale of Tenby International School in Setia Alam, core earnings jumped by half. Earnings were driven by progress billings at Setia Alam, Setia Eco Park, Bukit Indah and Setia Walk.
S P Setia’s sales remain strong, recording RM2.3 billion in new sales as at end-August, already surpassing its best ever full fiscal year sale. We expect the group to record sales above its bullish target of RM3 billion and FY11F earnings may exceed our current earnings forecast of RM311 million.

While latest monthly sales have dropped i.e. August figures dropped by some 12% month-on-month to RM186 million due to slower launches, sales are expected to rebound sharply in the next two months. S P Setia is expected to recognise the sale of the boutique offices in KL Eco City as the privatisation agreement with DBKL would be finalised soon. Sales from its maiden launch in Australia would also likely be accounted next month.
While there are a lot of uncertainties given the confidence crisis in the global economy, sector fundamentals remain solid. And S P Setia’s earnings are very much secured by record unbilled sales of RM3.9 billion (about two times its FY10 revenue). Should the economy turn, we believe sales would remain resilient and it has products to cater to the mass market; for example, Setia Alam and the recent land acquisition in Semenyih would provide more opportunities to launch mid-segment houses.
Following the weak sentiment, the stock has dropped by some 31% since its high of RM4.62. S P Setia is currently trading at a steep discount of 41% and an undemanding forward FY12F-FY13F PE of 11 to 14 times. We believe it is a good opportunity to accumulate the stock, notwithstanding the current weak market sentiment. — AmResearch, Sept 23
Wednesday, September 14, 2011
Bought Mahsing :p

Monday, August 8, 2011
Emerging Stocks Drop on U.S. Rating, Dragging Index Down 16% From May High

Very interesting market today. All covered with blood bath.
Saturday, July 30, 2011
Portfolio Update July 2011

July performance was good in the first three weeks, thanks to CI Holdings strong performance due to acquisition of its main subsidiary, Permanis by Asahi Group. However, due to poor market sentiment in the last week, some of my holding has taken the hit, led by Mahsing and YTLPower-WB.
Overall, both of portfolio still outperforming KLCI index.
Portfolio 1 = +21.9% (CIH, Mahsing, Padini)
Portfolio 2 = +43.6% (CIH, SOP, YTLP-WB)
Portfolio 1

Portfolio 2

Tuesday, July 26, 2011
Padini prepares for next growth phase
| Written by Joanne Nayagam |
| Monday, 25 July 2011 12:10 |
KUALA LUMPUR: The hustle and bustle at a Vincci shoe store, even during non-sale periods, is a telltale sign that local fashion company Padini Holdings Bhd has come some distance from its genesis as a simple garment maker four decades ago. Its success in making its mark on the local fashion scene goes beyond the homegrown shoe label to its other house labels like Seed and Padini Authentics.
Despite an upward trend in its momentum, however, the company is setting aside the next two years to iron out the creases in its supply chain and logistics. “One thing that we are looking at seriously is making sure that the existing doors have good growth rather than [to] keep expanding,” said CY Cheong, creative director with Padini, in a recent interview with The Edge Financial Daily.
The step back from expansion to consolidation mode to perfect its core mechanics, he said, is necessary to ensure the group can grow faster and more efficiently.
Despite the medium-term goal of perfecting its internal systems, Padini has scored well on its financial report card.
The last four years have seen uninterrupted growth, despite the 2008/09 financial crisis. Between 2006 and 2010, revenue has risen from RM286.11 million in 2006 to RM520.88, an average of 16.2% a year. Net profit surged from RM27.69 million to RM60.97 million, representing a 21.8% compound annual growth rate over the past four years.
Its market capitalisation stood at RM717.12 million as at last Friday’s RM1.09 close, being 10.58 times earnings for its current year ended June 30, 2011, according to Bloomberg data.
Indeed, some 40 years after its founding, Padini holds the enviable record as the largest and most profitable of Malaysia’s listed homegrown fashion companies. The company began in 1971 as a garment manufacturing and wholesale concern. It entered the retail industry in 1975 with its flagship brand Padini, while its other successful brand, Vincci, was established in 1986. Its other brands include PDI, Miki and Rope.
With its eye set to win more business in the region, Cheong said the group knows its operations at home need to run even more efficiently.
“I would say we are in quite a transitional stage of moving from a domestic-based company to regional. And for that, the way of working must change. The supply chain issue must be something we can address, because when you talk about doing business overseas, late delivery can sometimes be a problem, and also logistic[s],” said Cheong, adding that the company is constantly looking at increasing same store sales though physical store expansion may not be as aggressive for now. Money will still be spent to keep existing stores vibrant, to continue attracting customers while getting its existing loyal customers to buy more.
Even though overseas revenues currently contribute less than 10% to Padini’s total revenue, the Dubai Vincci store in Diera City Centre, is on par with the group’s best stores in Malaysia, such as at Mid Valley Megamall, Sungei Wang Plaza and Fahrenheit 88 (formerly KL Plaza) in Kuala Lumpur, Cheong said.

 |
| Cheong: I would say we are in quite a transitional stage of moving from a domestic-based company to regional. |
And there’s good promise for growth. Notably, Padini’s partners in the Middle East are local distributor heavyweights that also distribute more internationally-recognised labels. For instance, Al Shamsi Holdings Llc in UAE, Oman, Qatar and Bahrain handle Zara, Promod, Stradivarius and Women’s Secret, Cheong said. Padini also has other international partnerships in Morocco and Egypt.
He admits, though, that some of its partner operations abroad aren’t doing as well as the company would like due to certain gaps in its supply chain. The need to bridge these gaps was even more evident in the last six months, when the cost of manufacturing and raw materials escalated. As such, one of the group’s top priorities is to ensure smooth and efficient product movement, from manufacturing to delivery.
As a part of the internal restructuring process, Padini has invested in a management information system. In 2008, the company put out RM7.5 million to acquire the SAP enterprise resource planning system which allows it to streamline all its processes into fewer steps and coordinate sales based on past customer demands. “SAP has been implemented and we do see improvement and better control of our work process. We need probably another year for our users to get used to the system,” said Cheong.
As Padini develops its brand by creating a stronger foothold locally, the brand will continue to provide what has been the key to its growth thus far: adaptibility. “I think change is essential in order to keep the business moving,” said Cheong.
“It can be a big change, but you’ve got to feel that what your customers want and need is reflected in your product,” he said.
Tuesday, July 19, 2011
C.I. Holdings - I love it


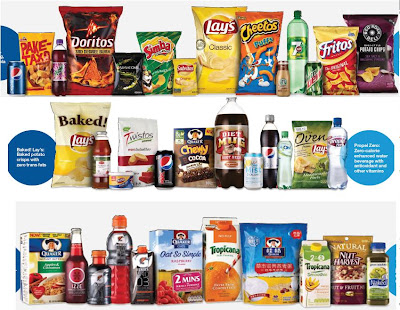
Brand Under Permanis = PEPSI, DIET PEPSI, TROPICANA TWISTER, LIPTON TEA, 7UP, BLUE MINERAL WATER, MOUNTAIN DEW, REVIVE ISOTONIC, BOSS COFFEE, MIRINDA, FROST & CHILLS.

Since the management already mentioned that they would like to expand further into full fledged F&B business, im expecting that they would like to introduce Frito Lays and Quaker Oat products more aggressively into Malaysian market. PepsiCo is widely know as the largest snack company through Frito Lays company. Thus, by having snack/food manufacturer company under CIH, would definitely complement their current business and create a better value to shareholders.
However, my only concern is acquisation of Permanis by Asahi, hopefully the management will put stop of this.
p/s = Tropicana Twister - Lychee, dont really like it, Fruit Tree Lychee much better. :p
Subscribe to:
Posts (Atom)