Showing posts with label Some Thought. Show all posts

Monday, February 28, 2011

Dutch Lady (3026)


This is another my favourite brand, i love their milk and yogurt drink and been drinking their milk since i dont know, maybe since i start loving milk. :p

The commodity price really hurt their Q4 earning, plus, like previous year Q4 sales normally lower than Q3. Looking at recent milk powder price trend, seems like their margin going to depress for next few months and they need to push for more sales in order to avoid slower net profit growth.

Overview of Milk industry (Dairy Commodity)

i) Global dairy product demand has increased. In particular, Asian nations’ improving economies have created desires for better, Western-style foods (more meat, more dairy). China’s basic food needs are drought-stressed.
ii) New Zealand’s milk output has been challenged by adverse weather.
iii) The U.S. dollar’s value has slumped, making foreign purchases of U.S. goods relatively cheaper.
iv) U.S. exporters (particularly cooperatives) have been giving away dairy products at prices far below global market values

Unlike automotive industry, normally they can pass a bit the impact to end user, which is us, the customer. Luckily my ex manager (my favourite boss of all time) currently managing the cost there, i might get some insight on the raw material & cost impact, if i decide to switch my other stock to DLADY. According to him, only special ingredient is imported from Netherlands, the rest mostly locally produced (the dairy product). Overall, Dlady managed to post a growth in sales in net profit FY2010.

In past 5 years, the lowest margin was 5.99%, back in 2008. Assuming that they manage to post small growth at 2.7% with net margin est at 6.5% (being defensive here), the est EPS would be 0.86. At current price of RM15.50, the forward PE ratio would be >18. Expensive!
Going forward, i think its worth to buy and hold as always reward a steady dividend to shareholders.But not at current price of course. Maybe below than RM15.00??

Dutch Lady PATMI (quarterly)

Dutch Lady Revenue (quarterly)
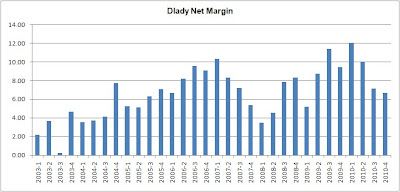
Dutch Lady Net Margin (quarterly)

Dutch Lady EPS and Gross DPS


Saturday, September 5, 2009

Update


I'm thinking to dispose my biggest holding, tgoffswa and swap to leader and affin bank next week. Not that im running out of cash, but saving for rainy day. havent decide yet but im considering this option ... if got volume la.

Tgoffswa +35.53%
Sealink +4.00%
Leader -3.87%
TM-CI +4.55%
Pelikan +33.91%
WTK -3.33%

Thursday, March 5, 2009

Amfirst

current price RM0.84
NAV Value RM0.99
div yield >8%

Maybe its time for me to buy amfirst for thier attractive dividend yield. Plus, theres no need to monitor much since always got coverage and news from ahbah in investlah.

Sunday, March 1, 2009

Trading Plan


First lets talk about pelikan..just for a quick review.Pelikan reported a rather disspointing result, not that i'm surprised since 4th quarter always the worst quarter for pelikan, as we can see from chart above. Cash and cash equivalent now stood around RM17.3m due to higher repayment of bank borrowing and payable. There's nothing new to talk about the balance sheet.

current price RM0.97
PE 7.2+
net asset ps 1.58 -7.06%
total liabilities -11.25%
payable -17.69% ( - 53.58m)
short term borrowing +16.49% (+23.31m)
repayment of bank borrowing -87.25m
proposed div 0.02sen

Overall the balance sheet is so so in comparison with other companies. Not sure i should dispose pelikan.Dividend yield also not attractive. However the only good betting on pelikan is its growth potiential due to recent restructing activities. Looks promising to me..imo.Hope the recent slump already factored in the market. Since my exposure in pelikan is very very low (thats why i dare to say i wanna hold pelikan earlier or else sure gone case :( )..so maybe i will keep them under my pillow. But then again money is still money (or maybe dispose them). Recession is getting worse. Hmmm...

Unlike pelikan, my exposure in TMI is quite big for a peanut investor like me ..hmmm.i tot TMI could fall below RM3 last friday. Giving me heachead already.

Parkson had a last hour bullish last friday..up 20 sen from my entry price. Not sure sustainable or not.Last friday was busy with my work, so din have much time to monitor my parkson ..hope i could sell at a nice price. TA wise..looks like forming a new uptrend line ? I'll not  talk more about this since my TA knowledge is not so good.

Since my health not so good since last few days ..fever, cough and flu , theres not much research i can do. maybe i'll just focus more on TMI and Affin.

Monday, February 2, 2009

Public Bank (1023)


Public Bank is my favourite bank and company in Malaysia.I'm using Public Bank and my first investment ever was with Public Bank :) PBBank going to pay share and cash dividend end of this month .Trading at 3x book value sounds risky but is it really worth to buy Pbbank just for thier dividend? TA wise also not attractive. What if I couldn't sell at profitable price after the ex date? Since I'm very unpredictible with decision, shall wait and see. Maybe I'm going to buy if the price looks attractive enough.

EX-date
:
26/02/2009
Entitlement date
:
02/03/2009
Entitlement time
:
05:00:00 PM
Entitlement subject
:
Final Dividend
Entitlement description
:
Final dividend of 25% less 25% income tax

EX-date
:
26/02/2009
Entitlement date
:
02/03/2009
Entitlement time
:
05:00:00 PM
Entitlement subject
:
Others
Entitlement description
:
Distribution of share dividend on the basis of 1 Public Bank ("PBB") treasury share listed and quoted as 'Local' on the Main Board of Bursa Malaysia Securities Bhd for every 35 ordinary shares of RM1.00 each held in PBB, fractions of treasury shares to be disregarded ("Share Dividend")


"Khoo said although Citigroup and Cazenove had downgraded their calls on PBB, Maybank-IB had maintained its buy call on the banking group’s current weakness, given that PBB was still the best among local banking groups in terms of performance.

“PBB is also not as exposed to external export markets and has a healthy balance in retail banking and trade financing, making it stronger in withstanding the global slowdown,” he said, adding that the banking group should still be giving high dividend yields compared with other local banking groups.

Nevertheless, he said there were expectations that Public Bank would lower its cash dividend this financial year to preserve capital in challenging times, and PBB might tap into its treasury shares again and distribute them to shareholders in place of a lower cash dividend.

Cazenove said PBB’s final dividend per share of 18.8 sen was significantly below the 40.8 sen expected in the market, and it would anticipate share price weakness on the counter.

“We cut our fair value from RM10.20 to RM7.40 based on a fair 2009 PBR (price-to-book ratio) of 2.5 times (versus the previous 3.5 times) from a higher cost of equity,” the research house said.

Cazenove added that it believed PBB’s strong double-digit earnings per share growth cycle since 2002 had peaked." The Edge Daily ~